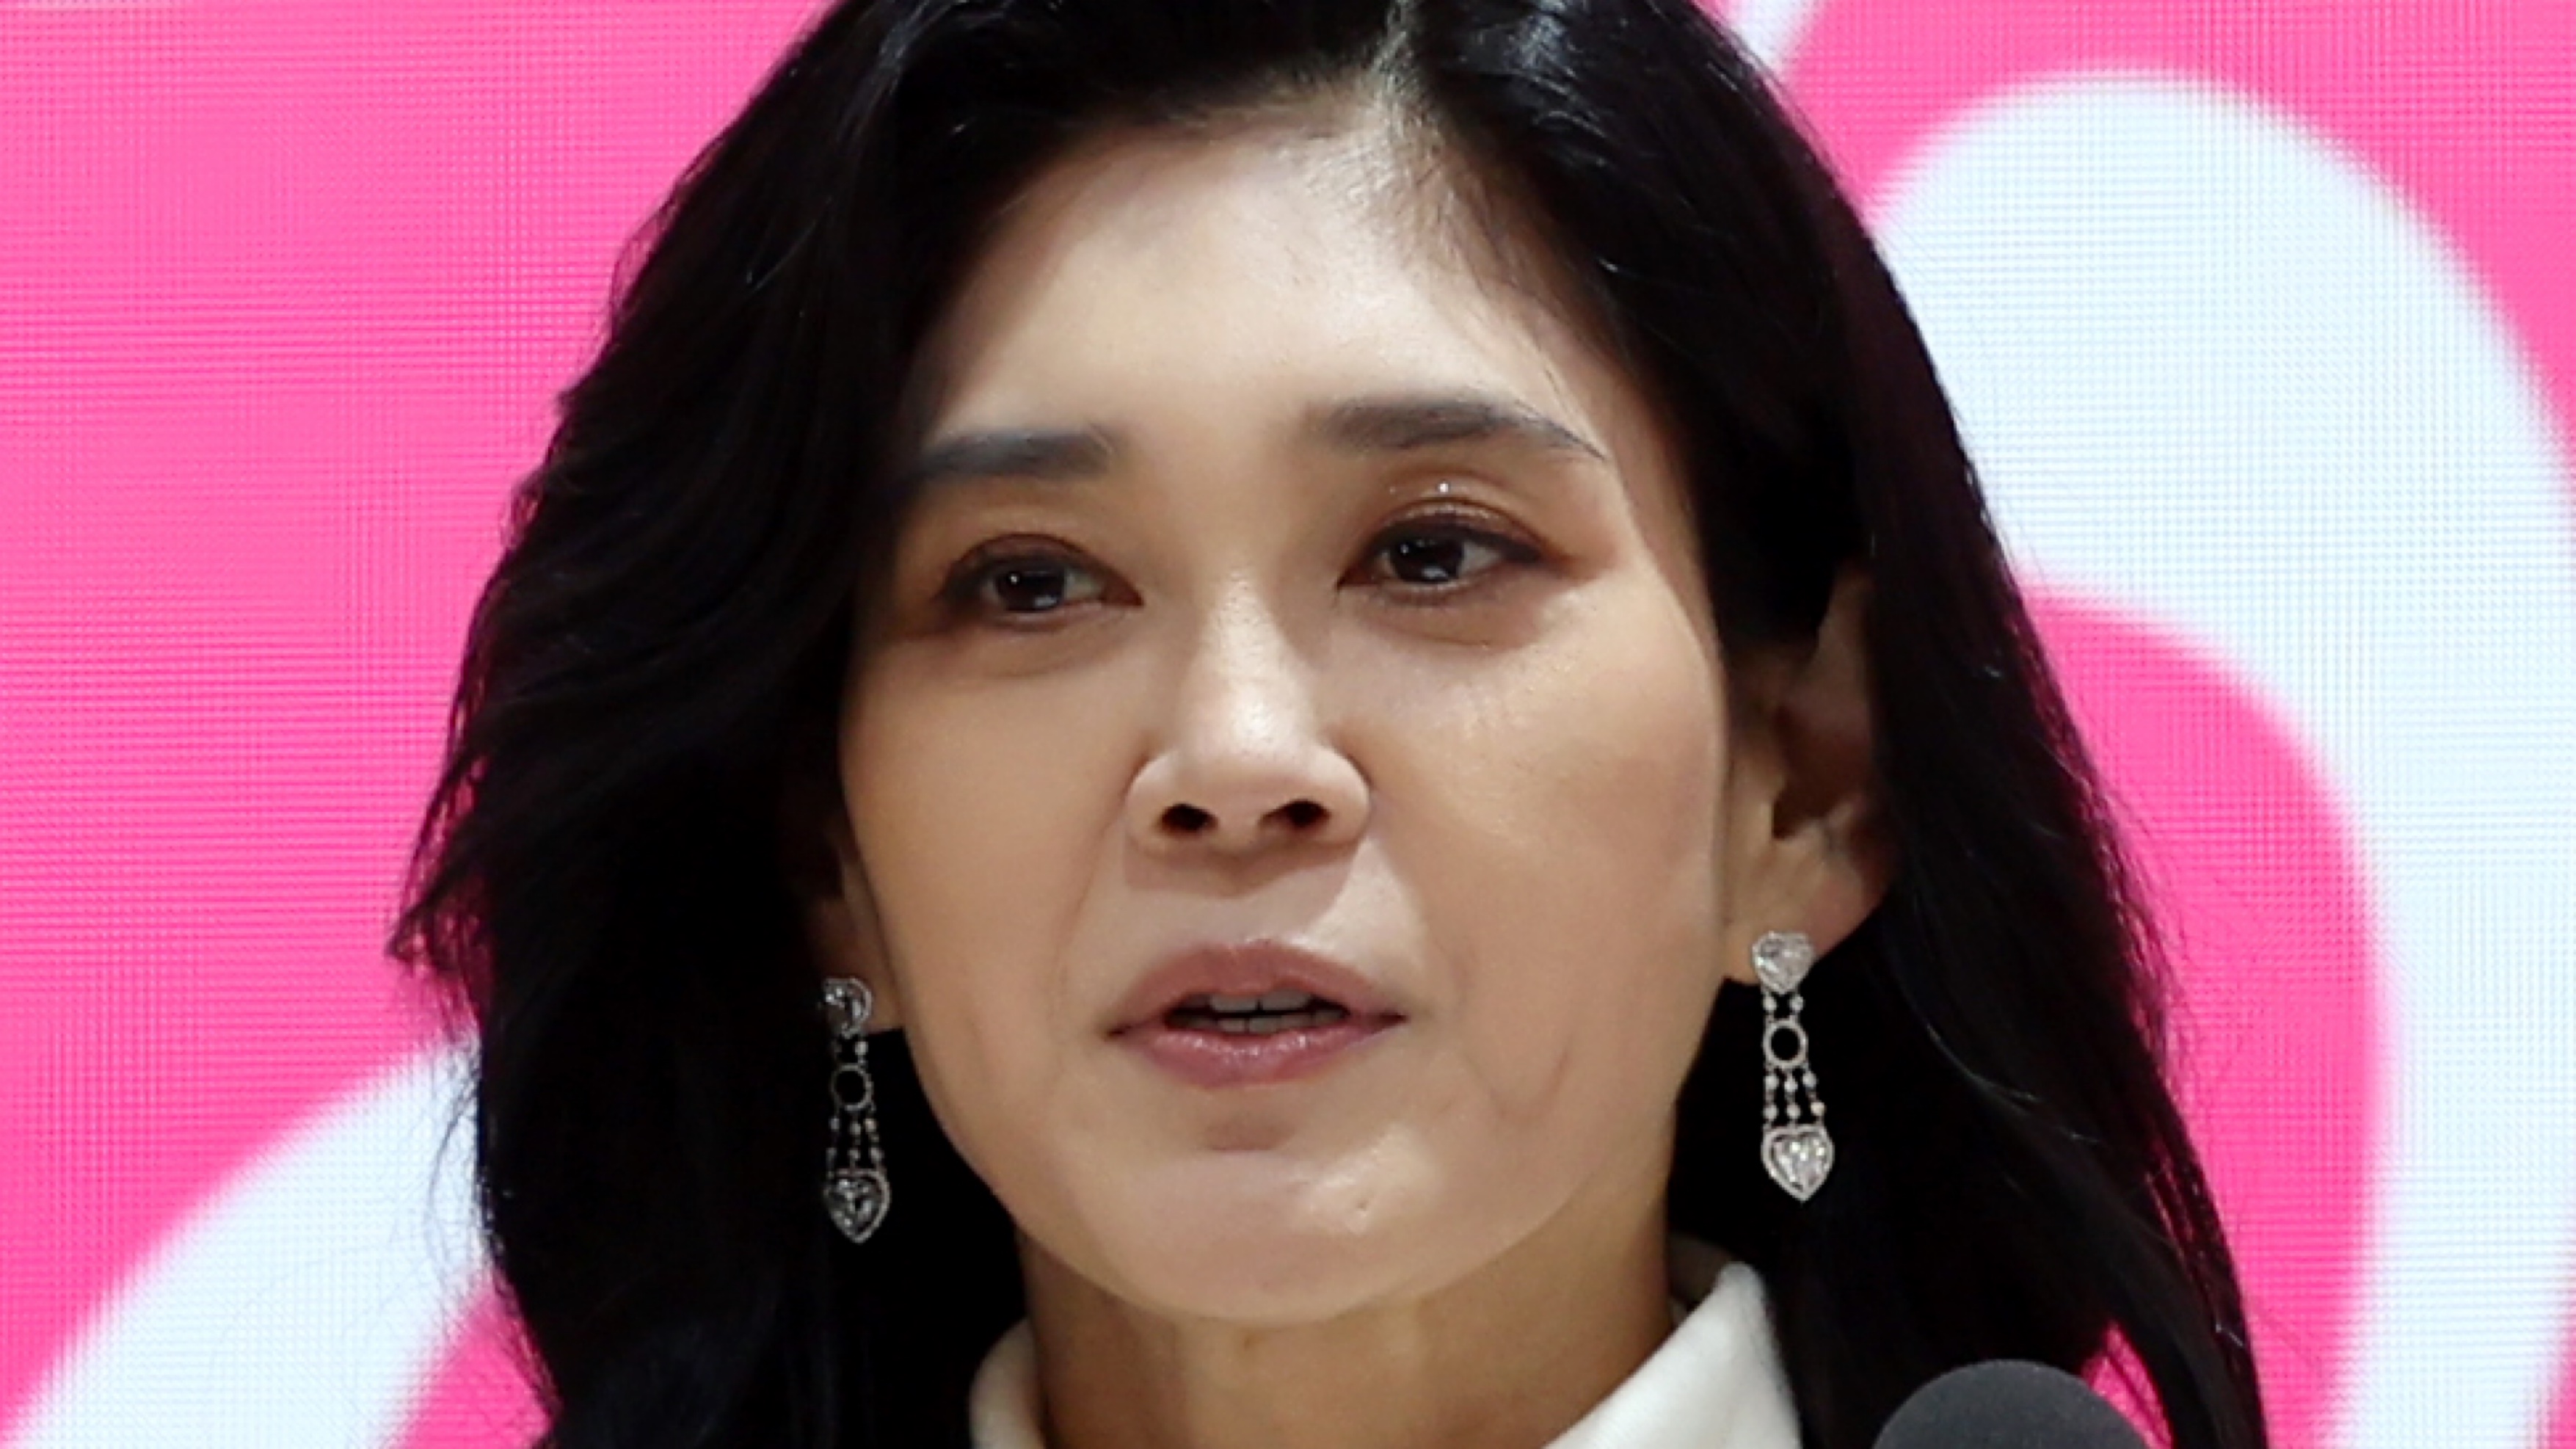
Lee Boo-jin, the 54-year-old president of Hotel Shilla Co., Ltd., launched a 30-day stock buyback program today worth 20 billion Korean won (approximately $14 million USD). She's purchasing 470,000 common shares, representing 1.18% of the company, entirely on the open market. This marks the first time Lee has bought shares of Hotel Shilla since taking the helm of the duty-free retail and luxury hotel conglomerate, a move that sends a clear signal to skittish investors after years of turbulent performance. The timing is strategic. Hotel Shilla just posted its first quarter 2026 earnings last week, revealing a dramatic turnaround. Revenue hit 1.05 trillion won, up 8.4% year-over-year, while operating profit reached 20.4 billion won, a complete reversal from the 2.5 billion won loss recorded in Q1 2025. The profit swing comes as China's travel recovery finally gained traction and South Korea's duty-free sector stabilized after years of brutal price competition and pandemic-era devastation. Han In-kyu, Hotel Shilla's president overseeing operations, preceded Lee's move by purchasing 200 million won worth of shares on March 23. While Han's buy was symbolic at roughly 1% of Lee's commitment, it established a pattern of executive confidence that Lee is now amplifying. The coordinated insider buying resembles a textbook playbook for signaling management's belief in an inflection point, particularly when institutional investors remain cautious about Korea's consumer spending outlook. Hotel Shilla operates two core businesses. The TR (travel retail) division runs duty-free stores at Incheon International Airport and downtown Seoul locations, competing directly with rivals like Lotte Duty Free and Shinsegae DF. The hotel division manages luxury properties including The Shilla Seoul, The Shilla Jeju, and boutique properties across South Korea. The duty-free segment has historically been the profit engine but suffered massive losses during COVID-19 border closures and hasn't fully recovered margins despite reopening. Lee's personal fortune and business legacy are inseparable from Samsung Group, where her late father Lee Kun-hee served as chairman until his death in 2020. She's part of the third-generation chaebol leadership navigating inheritance taxes, governance reforms, and public scrutiny of family wealth. By becoming a direct shareholder rather than just a hired executive, Lee is tying her personal capital to Hotel Shilla's performance in a way that Korean corporate culture interprets as ultimate accountability. The optics matter in a country where chaebols face relentless criticism over dynastic succession and perceived aloofness from ordinary investors.
 📈 business
Samsung Heiress Drops $14M on Own Stock
Lee Boo-jin, president of Hotel Shilla and daughter of Samsung's late chairman, is personally buying 20 billion won ($14 million) of her company's shares starting today. It's her first-ever stock purchase in the duty-free and hotel empire she runs, and it comes just as the company flipped back to profitability after bleeding cash last year.
My Take
This is Lee Boo-jin putting her money where her mouth is, and it's about damn time. Korean chaebols have spent decades insulating founding families from actual financial risk while retail shareholders ate losses. Lee buying $14 million of stock is pocket change for a Samsung family member, but it's the gesture that counts in a market where executives routinely dump shares the moment lockup periods expire. She's finally acting like an owner, not just a professional manager playing with house money. The real test is whether Hotel Shilla can sustain profitability without gimmicks. One profitable quarter doesn't erase years of mismanagement in the duty-free wars, where Korean retailers destroyed margins chasing Chinese tourist spending that evaporated when geopolitics turned ugly. If Lee is betting on a durable Chinese travel rebound, she's either seeing data the rest of us aren't or she's convincing herself that Xi Jinping will let middle-class Chinese resume splurging abroad. That's a risky bet. What makes this genuinely interesting is the succession angle nobody wants to discuss openly. Lee is demonstrating ownership mentality at a moment when Samsung's fourth generation approaches the spotlight. Her brother Lee Jae-yong runs Samsung Electronics, but the family's holdings span dozens of affiliates. If Hotel Shilla becomes a proof point for professional competence backed by personal capital commitment, it reshapes the narrative around hereditary business leadership in Korea's largest conglomerates. Lee isn't just buying stock. She's buying credibility for the next phase of chaebol evolution.
What Happens Next
Hotel Shilla's stock will get a short-term pop from the insider buying announcement, but the real action unfolds in May when Chinese Golden Week travel data drops. If mainland tourists flood back to Seoul's duty-free stores in numbers matching pre-2019 levels, Lee's bet looks prescient and the stock could rally another 15-20% by June. If Chinese spending stays tepid because domestic economic malaise keeps wallets closed, Lee will be sitting on an unrealized loss and facing uncomfortable questions at the next shareholder meeting. Watch for Lee to announce operational changes within 60 days. You don't drop $14 million on your own stock without a plan to juice performance metrics that Wall Street (and Korean retail investors) can track quarterly. Expect store renovations at Incheon Airport's duty-free zone, exclusive brand partnerships that competitors can't match, or a surprise pivot into digital duty-free platforms targeting younger Chinese consumers who book everything on WeChat. She needs visible wins to justify the confidence signal. The wild card is a potential Hotel Shilla subsidiary spinoff or asset sale by year-end. If Lee is genuinely committed to shareholder value rather than empire-building, she might dismantle underperforming hotel properties or carve out the TR division into a separately traded entity. That would unlock value the market currently ignores because it's buried in consolidated financials. It would also represent a radical break from chaebol tradition, where families hoard assets even when they destroy value. If Lee announces a spinoff in Q3 2026, it confirms she's playing a different game than her father's generation, and every other chaebol will face pressure to follow suit.
What History Tells Us
Lee Boo-jin's stock purchase echoes Warren Buffett's repeated open-market buys of Berkshire Hathaway shares during market downturns, most notably in March 2020 when Buffett signaled confidence in his portfolio companies by deploying personal capital. The difference is Buffett was buying his own holding company, while Lee is buying the operating company she manages, making the signal even stronger. In Korean corporate history, this resembles Chung Mong-koo's 2009 purchase of Hyundai Motor shares during the global financial crisis, a move that stabilized investor confidence when Korea's export economy looked shaky. Chung's buy preceded a multi-year rally in Hyundai stock, though it's debatable whether his purchase caused the recovery or simply coincided with broader auto sector stabilization. Lee is betting on a similar playbook in a very different industry.
Market Impact
Hotel Shilla (KRX: 008770) closed at approximately 50,900 won per share on April 25, 2026, down roughly 12% year-to-date as investors remained skeptical of the duty-free sector's recovery. Lee's 20 billion won buyback represents meaningful demand in a stock that trades around 15-20 billion won daily volume. Expect an immediate 5-8% gap-up when the Korean market opens Monday, April 28, as retail investors interpret insider buying as a bullish catalyst. The stock could test 55,000 won within two weeks if volume follows. Broader implications hit Korean retail and travel stocks. Lotte Shopping (023530.KS) and Shinsegae (004170.KS), which also operate duty-free divisions, will see sympathy moves as investors reassess whether Chinese tourism is genuinely recovering or if Lee is catching a falling knife. If Hotel Shilla sustains its rally, expect 3-5% gains across the travel retail sector. Conversely, if the stock fades after an initial pop, it confirms that one executive's stock purchase can't overcome structural headwinds in duty-free retail. The Korean won (KRW/USD) and Incheon International Airport-linked logistics stocks like Korea Airport Service (047810.KQ) get indirect boosts if Lee's bet validates a Chinese travel rebound thesis. Stronger Chinese tourist flows mean more foreign exchange inflows and higher airport throughput, which supports the won and aviation services stocks. However, this remains a second-order effect unless Q2 travel data confirms the trend. For now, Hotel Shilla is the direct play, with limited spillover unless the narrative expands.